Brightline Faces Financial Crossroads as Chapter 11 Filing Highlights the Challenges of Private High-Speed Rail Infrastructure

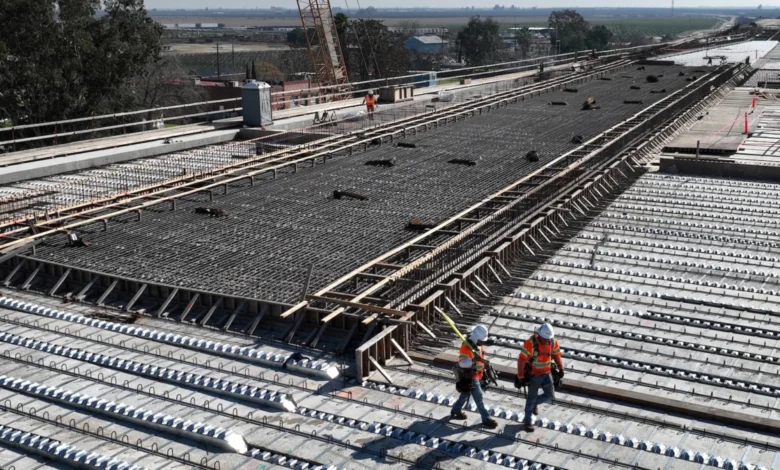
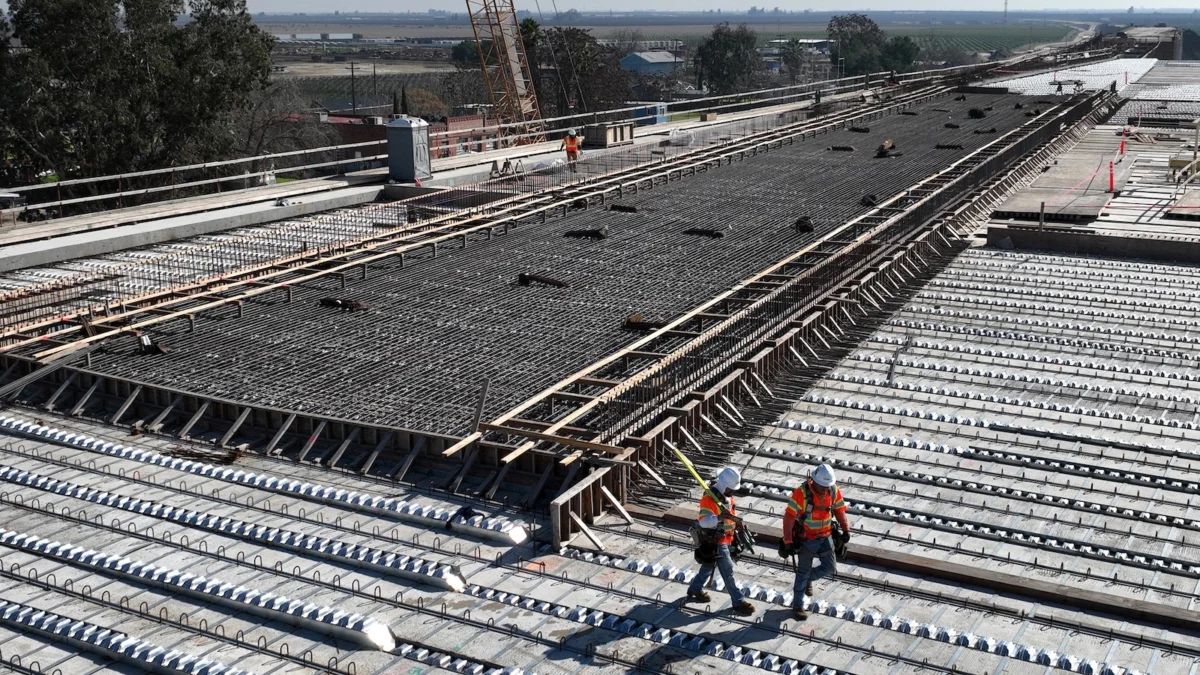
The first thing Brightline wants you to know about its bankruptcy is that the trains will keep running. For the thousands of daily commuters and travelers who rely on the vibrant yellow trains traversing the Florida peninsula, the message from company leadership is clear: it is business as usual. However, beneath the surface of this operational continuity lies a complex financial restructuring process that underscores the precarious nature of financing large-scale, high-speed rail projects through private capital in the United States.
Brightline’s recent filing for Chapter 11 bankruptcy protection follows months of intensive, behind-the-scenes negotiations with bondholders. The move is designed to provide the privately operated rail line with the necessary breathing room to secure an additional $490 million in financing. This infusion of capital is deemed essential for the company to manage its staggering $4.4 billion debt load—a liability accumulated through the intensive costs of engineering, land acquisition, construction, and operational scaling since the project’s inception.
Operational Resilience Amidst Restructuring
A critical distinction in this legal maneuver is the scope of the filing. The bankruptcy protection applies specifically to the holding entities responsible for the debt, while the operational arm—Brightline Trains Florida—remains unaffected. Consequently, the high-speed service between Orlando and Miami, which reaches speeds of up to 125 mph, continues its schedule without interruption. Similarly, the project’s sister venture, Brightline West, which is currently developing a high-speed corridor between Las Vegas and the Los Angeles metropolitan area, remains insulated from the current restructuring.
The project has long been hailed as a potential blueprint for American infrastructure, particularly in regions where public transit options have historically been sparse and capital investment has been hesitant. Since its inaugural service between Miami and West Palm Beach in 2018, Brightline has expanded its footprint to Orlando in 2023, with future extensions planned for Tampa and a new stop in Cocoa. The system has demonstrated consistent growth, recording a 14 percent increase in ridership and a 17 percent rise in revenue between January and August 2026 compared to the same period the previous year.
The Debt-to-Revenue Disconnect
Despite the upward trajectory in passenger demand, financial analysts suggest that the company’s revenue growth has failed to keep pace with the massive upfront costs of rail development. According to Tim Hynes, head of Global Credit Research at Debtwire, Brightline currently serves approximately 3.5 million passengers annually and generates roughly $240 million in revenue. These figures, while impressive for a private rail startup, represent less than half the projected ridership and only one-third of the revenue targets established for 2024.
This disparity explains why the company has found it necessary to rework its balance sheet. The immense capital expenditure required for rail infrastructure—which includes the construction of tracks, signaling systems, stations, and specialized rolling stock—creates a "debt-heavy" business model that is difficult to sustain without significant long-term ridership or government support.
A Chronology of Growth and Obstacles
The journey of Brightline began in the mid-2010s with the vision of revitalizing Florida’s transit landscape. The following timeline outlines the major milestones of the project:
- 2018: Brightline launches service between Miami and West Palm Beach, marking the first time in over a century that a private company has operated an intercity passenger rail service in the U.S.
- 2019-2021: Construction ramps up for the Orlando extension, even as the global pandemic forces a temporary suspension of service.
- 2023: Full service begins between Miami and Orlando, connecting two of Florida’s most significant economic and tourism hubs.
- 2024-2025: Ridership trends show steady improvement, yet the burden of the debt incurred during the construction phase becomes increasingly difficult to service.
- 2026: Facing a critical juncture in debt repayment, the company files for Chapter 11 protection to facilitate a $490 million financial restructuring.
Safety and Public Perception
While the financial news dominates headlines, the project has not been without controversy. Since 2018, the rail line has been linked to 182 fatalities, many occurring at grade crossings or involving individuals on the tracks. These incidents have drawn significant scrutiny from local officials and community advocacy groups. In response, Brightline has consistently maintained that none of these fatalities were caused by operational failures or mechanical errors. The company has invested hundreds of millions of dollars into safety infrastructure, including improved signage, fencing, and advanced signaling technology at high-risk crossings.
Despite these challenges, the consumer experience remains a strong selling point. Ivan Reich, a frequent traveler and bankruptcy attorney who commutes between West Palm Beach and Fort Lauderdale, describes the experience as a premium alternative to traditional transit. "Brightline is literally like going to the airport and being on a plane," he remarked. "It is a luxury experience. It’s nice. It’s pleasant. It’s comfortable." For passengers like Reich, the primary hurdle remains the cost, which can fluctuate between $35 for a short commute and upwards of $120 for round-trip intercity travel, a price point that makes it a premium service rather than a mass-transit utility.
Implications for the Future of Rail
The broader question triggered by Brightline’s financial situation is whether private enterprise alone can bear the weight of American infrastructure development. With Amtrak setting consecutive ridership records and demand for rail travel surging, the appetite for high-speed transit is clearly present. However, the model of the private operator—even one as successful as Brightline—may face inherent limits when compared to the government-subsidized systems seen in Europe and Asia.
This tension is most visible in the development of Brightline West. The $21 billion project to connect Las Vegas and Rancho Cucamonga has already secured a $3 billion federal grant and is currently seeking an additional $6 billion federal loan. The project’s reliance on these public funds highlights a growing consensus: large-scale rail infrastructure requires a hybrid model where public investment serves as the foundation for private innovation.
Expert Perspectives on Public-Private Partnerships
Industry experts are divided on the long-term viability of the current model. Jim Mathews of the Rail Passengers Association views the Chapter 11 filing as a pragmatic step that allows the company to shed an unsustainable debt burden. However, he warns that this does not solve the underlying issue of systemic underinvestment. "Building a railroad is very hard and very expensive," Mathews stated. "This is a good example of why governments always have a legitimate role to play."
Alon Levy, a research scholar at the NYU Marron Institute, points to the logistical challenges of integration. The decision for the Brightline West line to terminate in the suburb of Rancho Cucamonga, rather than central Los Angeles, highlights the difficulty of connecting private lines to existing public commuter networks like Metrolink. According to Levy, "top-down federal action" is required to ensure that disparate systems can function as a cohesive national network.
Furthermore, Rick Harnish of the High Speed Rail Alliance argues that the American approach to transportation funding is fundamentally lopsided. By treating rail as a purely private endeavor while heavily subsidizing highways and airports through public taxation, the U.S. has created an uneven playing field. "Private capital will not invest in the kind of infrastructure you need to fund public transit," Harnish noted. "It’s time for both the feds and states to start investing in good, high-quality tracks."
Conclusion: The Road Ahead
As Brightline moves through its restructuring, the company remains a central pillar of Florida’s transportation network. CEO Patrick Goddard has expressed confidence that the transition will serve as a "catalyst for further growth." Yet, the challenges facing the company are reflective of a larger, national dilemma. As the United States looks toward a future of reduced carbon emissions and increased connectivity, the lessons of Brightline will be essential. The fundamental question remains: who will pay for the tracks? Whether the answer lies in more robust public-private partnerships or a shift toward greater federal infrastructure spending, the success of the next generation of high-speed rail depends on finding a sustainable, long-term fiscal framework that recognizes the rail system as a public good rather than just a private commodity.
Related posts: