The Great Data Center Illusion: Why Billions in AI Infrastructure Investments May Never Materialize

The relentless global boom in artificial intelligence infrastructure is colliding with a harsh reality check. While headlines regularly trumpet multibillion-dollar announcements for new data center campuses, power grid upgrades, and specialized hardware fabrication plants, industry experts warn that a substantial portion of these ambitious proposals face insurmountable hurdles. Beyond the well-documented roadblocks—including widespread local community opposition, bureaucratic permitting delays, and an unprecedented, frantic scramble for localized electricity generation—lies a more fundamental and understated problem: many of the data center projects currently announced may never actually break ground.
As trillions of dollars in global capital chase the promise of generative AI, distinguishing between viable, high-probability infrastructure projects and speculative, pie-in-the-sky announcements has become an urgent priority for investors, utility providers, and policymakers alike.
The Anatomy of a Speculative Boom
To understand the current state of the data center market, one must look at the unprecedented velocity of capital deployment. Following the mainstream breakthrough of advanced large language models, technology giants, sovereign wealth funds, and specialized real estate investment trusts (REITs) have rushed to secure land, water rights, and power interconnection queues.
However, this gold-rush mentality has created a distorted market. A significant percentage of announced data center developments are speculative land grabs or "placeholder" filings. Developers often submit interconnection requests to regional transmission organizations (RTOs) and independent system operators (ISOs) long before securing final financing, hardware supply chains, or municipal zoning approvals. These speculative filings clog up administrative pipelines, creating a massive administrative backlog that penalizes serious developers whose projects are genuinely ready for execution.
Industry analysts point out that securing a plot of land and issuing a flashy press release does not equate to a functioning data center. The modern AI data center requires unprecedented density, often demanding hundreds of megawatts—or even gigawatts—of continuous power, sophisticated liquid-cooling infrastructure, and ultra-low-latency fiber optic connectivity. Without these foundational elements locked down, an announced facility remains nothing more than digital ink on a blueprint.
Grid Strain, Local Resistance, and Permitting Gridlock
The physical limitations of modern infrastructure are exerting severe pressure on the AI expansion narrative. Power grids across North America and Europe are experiencing historical stress tests. In major hubs such as Northern Virginia—often referred to as "Data Center Alley"—and emerging markets in Texas and the Midwest, local utilities are struggling to reconcile the astronomical power demands of upcoming server farms with existing generation capacity.
In Texas, regulatory shifts have begun to reflect the growing friction between rapid tech expansion and grid stability. State officials and regional operators have increasingly scrutinized new large-load connections, implementing stricter audits and, in some cases, halting new data center queue approvals until comprehensive resource adequacy studies can be completed.
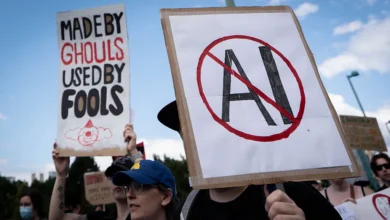
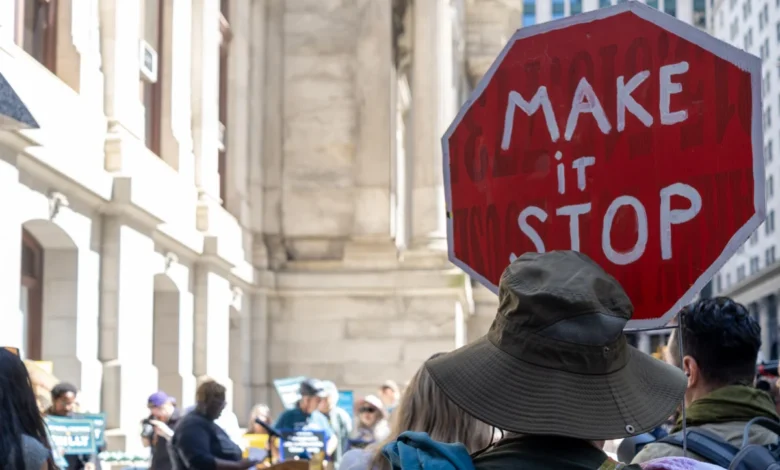
Simultaneously, local opposition has transitioned from a localized nuisance into a coordinated political movement. Communities near proposed mega-sites are raising concerns regarding noise pollution from industrial-scale cooling fans, strain on local municipal water supplies, and the aesthetic degradation of rural and suburban landscapes. Furthermore, environmental advocates frequently push back against the carbon-intensive nature of powering massive AI clusters, especially in regions where grid operators remain heavily reliant on fossil fuels. These community pushbacks frequently result in prolonged litigation, zoning board denials, and significant permitting delays that can bleed millions of dollars from a project’s balance sheet before construction even begins.
Separating Reality from Speculation: Insights from the Field
Addressing these mounting complexities requires a rigorous methodology for evaluating infrastructure viability. On an episode of TechCrunch’s Equity podcast, hosts Rebecca Bellan and Tim De Chant welcomed Brent Nelson, senior managing director of markets and strategy at Ascend Analytics, to dissect the intricacies of the data center pipeline.
During the discussion, Nelson emphasized that the market must develop better diagnostic tools to separate robust projects from speculative ventures. According to Nelson, financial backing alone is insufficient if a project lacks a realistic path to power procurement. In an era where power availability is the ultimate bottleneck, a data center without an ironclad power purchase agreement (PPA) or a prioritized spot in an interconnection queue is essentially an unviable asset.
The conversation highlighted that sophisticated investors are shifting their focus away from pure software plays and toward the underlying energy technology sector. Investments in next-generation nuclear energy, advanced geothermal systems, long-duration energy storage, and grid-enhancing technologies are increasingly viewed as the true prerequisites for sustained AI growth. If the energy infrastructure cannot scale reliably, the data centers meant to house the compute power will remain dark.
Chronology of the Infrastructure Crunch
- Early 2023: Following the viral adoption of generative AI applications, tech enterprises begin exponentially increasing capital expenditure projections for data center capacity.
- Late 2023 to Early 2024: Regional transmission organizations report record-breaking numbers of interconnection requests, causing massive administrative backlogs in major U.S. power grids.
- Mid 2024 to 2025: Local communities increasingly organize against proposed mega-campuses, citing grid reliability fears and water usage concerns. Municipalities begin enacting moratoriums and stringent zoning restrictions.
- Early 2026: Regulatory bodies, such as those in Texas, begin halting or pausing new data center queue entries to audit grid capacity and ensure resource adequacy.
- Mid 2026: Market analysts and financial experts pivot toward energy technology investments, recognizing that power availability—rather than capital availability—is the ultimate limiting factor for AI expansion.
Broader Implications for the Tech and Financial Sectors
The divergence between announced projects and realized construction carries profound implications for the global economy. For venture capitalists, private equity firms, and institutional investors, misjudging the viability of an infrastructure portfolio can result in catastrophic capital write-downs. As regulatory scrutiny tightens and utility providers demand more skin-the-game from developers—such as higher upfront deposits for grid interconnection studies—the era of speculative land-banking for data centers is drawing to a close.
Moreover, the tech industry’s insatiable appetite for electricity is forcing a reluctant marriage between Silicon Valley and the traditional energy sector. Technology conglomerates are increasingly bypassing standard utility frameworks to directly finance nuclear reactors, sign direct-to-source renewable energy deals, and invest heavily in grid modernization hardware.
Ultimately, the ongoing data center boom will undergo a painful but necessary period of consolidation. The projects that survive will be those backed by rigorous engineering, secure and sustainable power sourcing, and proactive community engagement. Those built solely on speculative hype and favorable press releases will quietly vanish from the development pipeline, serving as a cautionary tale of overzealous capital allocation in the age of artificial intelligence.